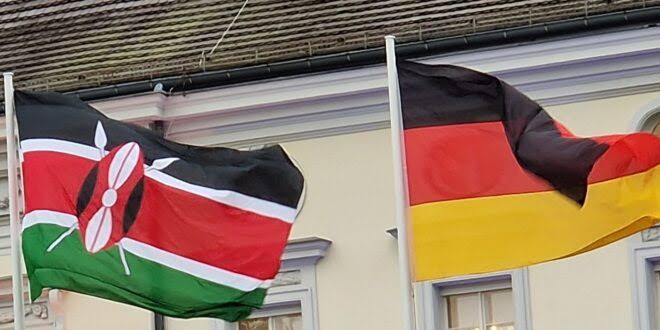

Kenya and Germany are working to resolve outstanding tax exemption issues and finalise implementation agreements for a digital transformation programme aimed at strengthening Kenya’s digital economy.
The discussions took place during a meeting between Eng. John Kipchumba Tanui, Principal Secretary in Kenya’s State Department of ICT and Digital Economy, and a delegation from German development agency Deutsche Gesellschaft für Internationale Zusammenarbeit (GIZ) GmbH.
The delegation included Dr Christoph Zipfel, Programme Director for Sustainable Economic Development, and Sylvia Lautenbach, who was formally introduced as the new Programme Director and Acting Programme Manager for the Digital Transformation Centre II (DTC II) programme.
The meeting focused on completing the programme’s implementation agreements after Kenya’s National Treasury provided feedback. Both sides also discussed unresolved tax exemption matters that could affect the programme’s implementation.
The discussions highlight a key challenge facing international digital development partnerships: securing funding and technical expertise is only part of the process, while resolving administrative and fiscal issues is essential to turning agreements into practical results.
For Kenya, the outcome of the negotiations could influence how quickly the programme moves from planning to implementation, particularly as the government seeks to strengthen digital infrastructure, improve public institutions’ technological capabilities and expand opportunities for innovation.
Tanui stressed the importance of ensuring that international partnerships deliver tangible benefits for Kenya’s digital economy rather than remaining at the level of policy discussions.
The DTC II programme forms part of broader cooperation between Kenya and Germany to advance digital transformation, strengthen institutional capacity and support inclusive economic growth.

The programme’s progress will depend in part on how quickly the two sides resolve the outstanding issues and establish the arrangements needed to implement their agreed activities.
Although the meeting signals continued cooperation, the parties have not disclosed a final resolution of the tax exemption questions or a definitive timeline for completing the implementation agreements.